
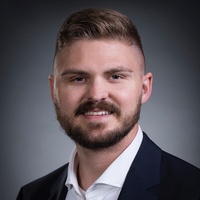
Is the classic 60/40 portfolio still enough? On the Tall Oaks Podcast, Branden DuCharme sat down with Charlie McGarraugh, Chief Investment Officer of Altis Partners, to talk about managed futures, trend following, leverage, and what diversification can look like beyond stocks, bonds, and cash. Charlie’s career spans 16 years at Goldman Sachs, where he became a Partner and Global Head of Metals Trading, as well as time as Chief Strategy Officer at Blockchain.com. The views below are Charlie’s, shared in conversation.
Why the 60/40 portfolio is getting a second look
For decades, bonds did two jobs in a 60/40 portfolio. They paid income, and they often rose when stocks fell. Falling interest rates helped for a long stretch, and the stock-bond correlation was persistently negative.
Charlie explained that this relationship changed around 2020 to 2021. His framework: when growth expectations drive markets, stocks and bonds tend to move in opposite directions. When uncertainty about liquidity and money in the system dominates, they tend to move together. That is why the same portfolio can behave very differently depending on which story the market is telling.
The takeaway Charlie offered was a question, not a prediction. If the stock-bond correlation can shift, how much should an investor lean on bonds as a hedge?
Diversified on growth, but diversified on inflation?
One of Charlie’s clearest points: if the only tools in your toolkit are stocks, bonds, and cash, you may be diversified on growth but not on inflation. Inflation is hard on all three.
He described two broad ways to respond. One is to add different exposures, such as real assets and upstream commodity exposure (the inputs and bottlenecks in a supply chain, rather than only companies at the end of it). The other is to behave differently with what you already own, being more adaptive instead of fully static.
How leverage works in futures
Charlie noted that futures are structurally leveraged, because you post margin rather than the full value of the exposure. He used a simple gold example: two people can bet on the price of an ounce of gold without each putting up the full price.
He was clear about the other side. Leverage is “like fire.” It can be useful, but it requires respect, analysis, and attention.
On concerns about counterparties, Charlie pointed to the long history of futures markets and the role of clearinghouses, and described futures as generally liquid with transparent daily pricing. He contrasted that with private investments, where marks can be harder to verify and access to your money can be slower.
Trend following: “the moving business”
Charlie described trend following with a metaphor. Buying and holding stocks or bonds is like the storage business. Trend following is the moving business. Sometimes when storage isn’t doing well, moving does better. He was also candid that it can be episodic, with long stretches that feel like chop before a trend appears.
He also described trend following as one of many risk premia a systematic manager might use, and noted that a diversified futures program tries to hold many independent bets, not just one.
Why Charlie says risk is easier to predict than returns
One of the more practical ideas in the conversation: it is generally easier to forecast how volatile something will be than which direction it will go. So even without strong views on direction, adjusting exposure as volatility changes can be a meaningful part of managing a portfolio.
The risks to understand first
Charlie highlighted two:
Sudden reversals. Trend-following systems can struggle when markets reverse quickly.
Bankroll management. Leverage requires discipline. Concentrated bets that are too big for your capital are what can do permanent damage, in his view.
He also stressed that managers should do what they say they will do, since style drift is a real issue.
Key takeaways
The stock-bond relationship isn’t fixed, and that matters for 60/40.
Stocks, bonds, and cash alone may leave an inflation gap.
Futures have leverage built in, which can be useful or dangerous.
Trend following is one approach and is episodic by nature.
Risk management matters more than any single idea.
FAQ
What are managed futures? Strategies that trade futures contracts across markets such as bonds, stock indexes, currencies, and commodities, often using systematic, data-driven rules. Charlie discusses them in this episode as a potential diversifier, not a guarantee of any outcome.
What is trend following? A systematic approach that tries to benefit from sustained price moves up or down. Charlie calls it “the moving business.”
Why is the 60/40 portfolio being questioned? Because the stock-bond correlation that helped it for decades has changed, and because inflation is hard on stocks, bonds, and cash.
Is leverage in futures risky? Yes. Charlie compares leverage to fire: powerful if used carefully, damaging if not. He emphasizes bankroll management.
Listen and watch
Youtube: https://www.youtube.com/@TallOaksPodcast
Also see our recent conversation with Harley Bassman on convexity: https://ducharmewealth.com/harley-bassman-on-bonds-ai-debt-and-inflation-takeaways-from-tall-oaks-podcast/